Does GBPJPY have days, months or hours with a bias you can actually measure? We aggregated 4,391,067 M1 candles of sterling against the yen, the most volatile G10 cross from January 2015 to October 12, 2026 by day of week, calendar month, session and UTC hour, and ran every result through a significance test. Bottom line: 2 of the 17 calendar buckets come out at p < 0.05, but none survives a multiple-comparison correction. A hint, not a rule.
📊 The data behind this article, as tables and CSV: /stats/GBPJPY publishes GBPJPY seasonality, sessions and spread as a downloadable reference, and /data has the OHLCV candles (D1 down to M1) so you can replicate every table. This article is the analysis, with its tests; those pages are the raw numbers.
1. Seasonality by day of the week
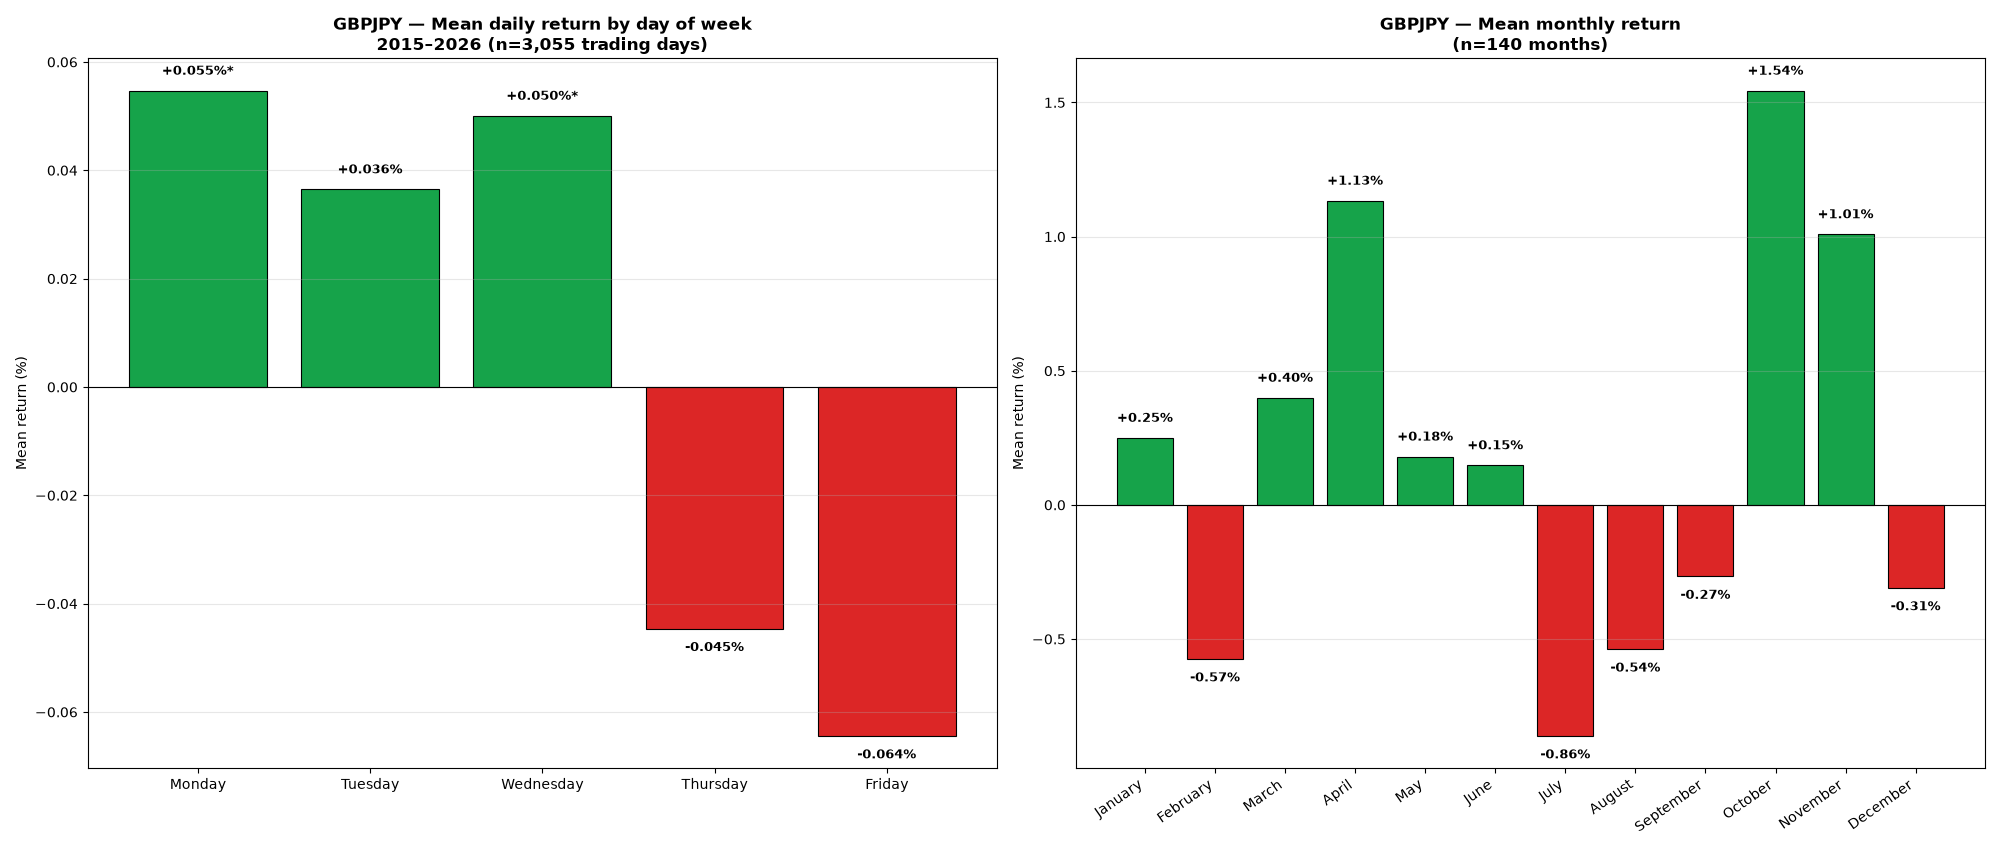
Each day closes at 22:00 UTC, a fixed hour present in every year of the feed. Test: one-sample t-test against zero; bold marks what survives a Bonferroni correction.
⚠️ Mid price, not bid. In GBPJPY, the spread on Friday's last candle is 6.4 times the usual one. Measured on the bid, that close comes out artificially low and Monday seems to bounce: a "Monday effect" made by the spread, not the market. That is why every close is taken at mid price (bid+ask)/2. If you see a Monday bias in another FX study, check which price it uses.
| Day | n | Mean % | Median % | Std % | Win rate | t-stat | p-value |
|---|---|---|---|---|---|---|---|
| Monday | 611 | +0.055% | +0.057% | 0.612% | 55.6% | 2.21 | 0.028 |
| Tuesday | 612 | +0.036% | +0.030% | 0.651% | 53.1% | 1.39 | 0.166 |
| Wednesday | 610 | +0.050% | +0.062% | 0.614% | 56.1% | 2.01 | 0.044 |
| Thursday | 612 | -0.045% | -0.054% | 0.664% | 44.9% | -1.66 | 0.097 |
| Friday | 610 | -0.064% | -0.001% | 0.820% | 50.0% | -1.94 | 0.053 |
Reading: days with p < 0.05:
- Monday: +0.055% on average, 55.6% win rate, p=0.028, but it does not clear the Bonferroni threshold for 5 tests (0.0100). Across the two halves of the sample (2015–2020: -0.022%; 2020–2026: +0.131%) the sign flips, so it is not stable.
- Wednesday: +0.050% on average, 56.1% win rate, p=0.044, but it does not clear the Bonferroni threshold for 5 tests (0.0100). Across the two halves of the sample (2015–2020: +0.041%; 2020–2026: +0.060%) the sign holds.
2. Seasonality by month of the year
140 complete months (the current month is left out). Each month's return = last close of the month against the last close of the previous month.
| Month | n | Mean % | Median % | Std % | Win rate | t-stat | p-value |
|---|---|---|---|---|---|---|---|
| January | 11 | +0.25% | +0.33% | 2.02% | 54.5% | 0.41 | 0.689 |
| February | 12 | -0.57% | -0.50% | 3.93% | 41.7% | -0.51 | 0.623 |
| March | 12 | +0.40% | +0.53% | 2.47% | 58.3% | 0.56 | 0.586 |
| April | 12 | +1.13% | +1.25% | 2.38% | 75.0% | 1.65 | 0.127 |
| May | 12 | +0.18% | +0.92% | 2.92% | 58.3% | 0.21 | 0.835 |
| June | 12 | +0.15% | +1.21% | 4.89% | 83.3% | 0.11 | 0.918 |
| July | 12 | -0.86% | -0.64% | 2.21% | 33.3% | -1.35 | 0.205 |
| August | 12 | -0.54% | -0.42% | 1.83% | 33.3% | -1.02 | 0.331 |
| September | 12 | -0.27% | -0.43% | 2.98% | 50.0% | -0.31 | 0.762 |
| October | 11 | +1.54% | +1.87% | 2.77% | 72.7% | 1.85 | 0.094 |
| November | 11 | +1.01% | +0.80% | 4.06% | 63.6% | 0.82 | 0.429 |
| December | 11 | -0.31% | +0.90% | 3.17% | 63.6% | -0.32 | 0.753 |
Reading: no month reaches p < 0.05. The best on average is October (+1.54%) and the worst July (-0.86%), but with 11 observations per month a single extreme year moves those averages a lot.
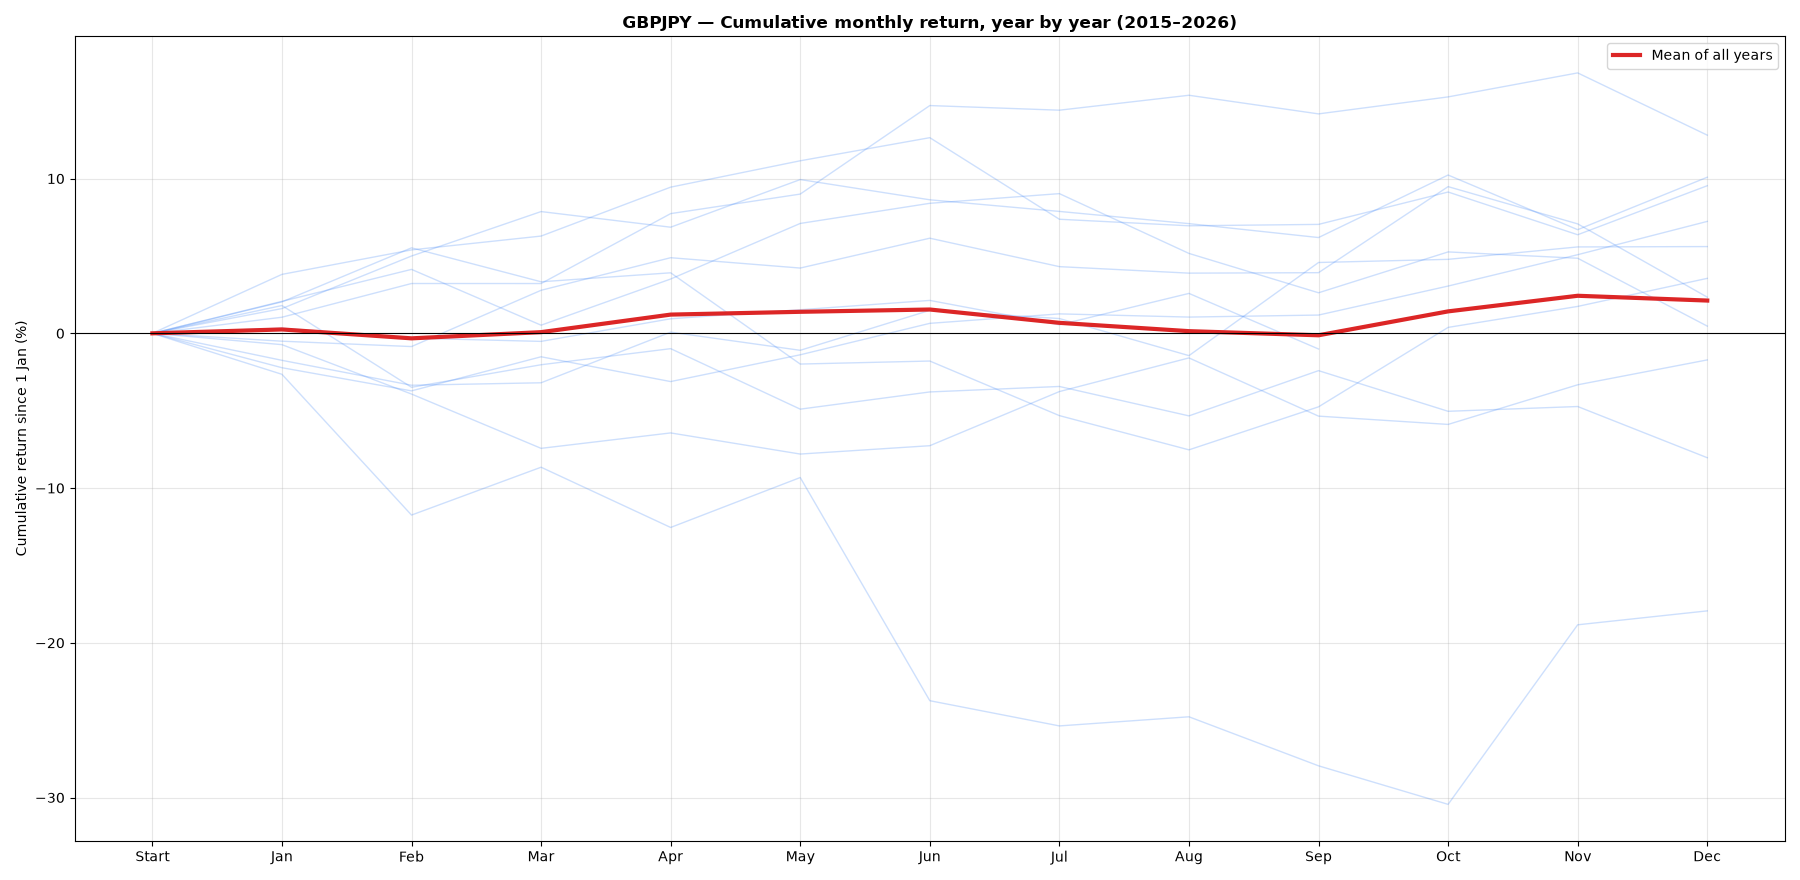
Each thin line is one year; the red one is the mean. When the thin lines fan out, a month's average says little about next year.
3. Seasonality by trading session (UTC)
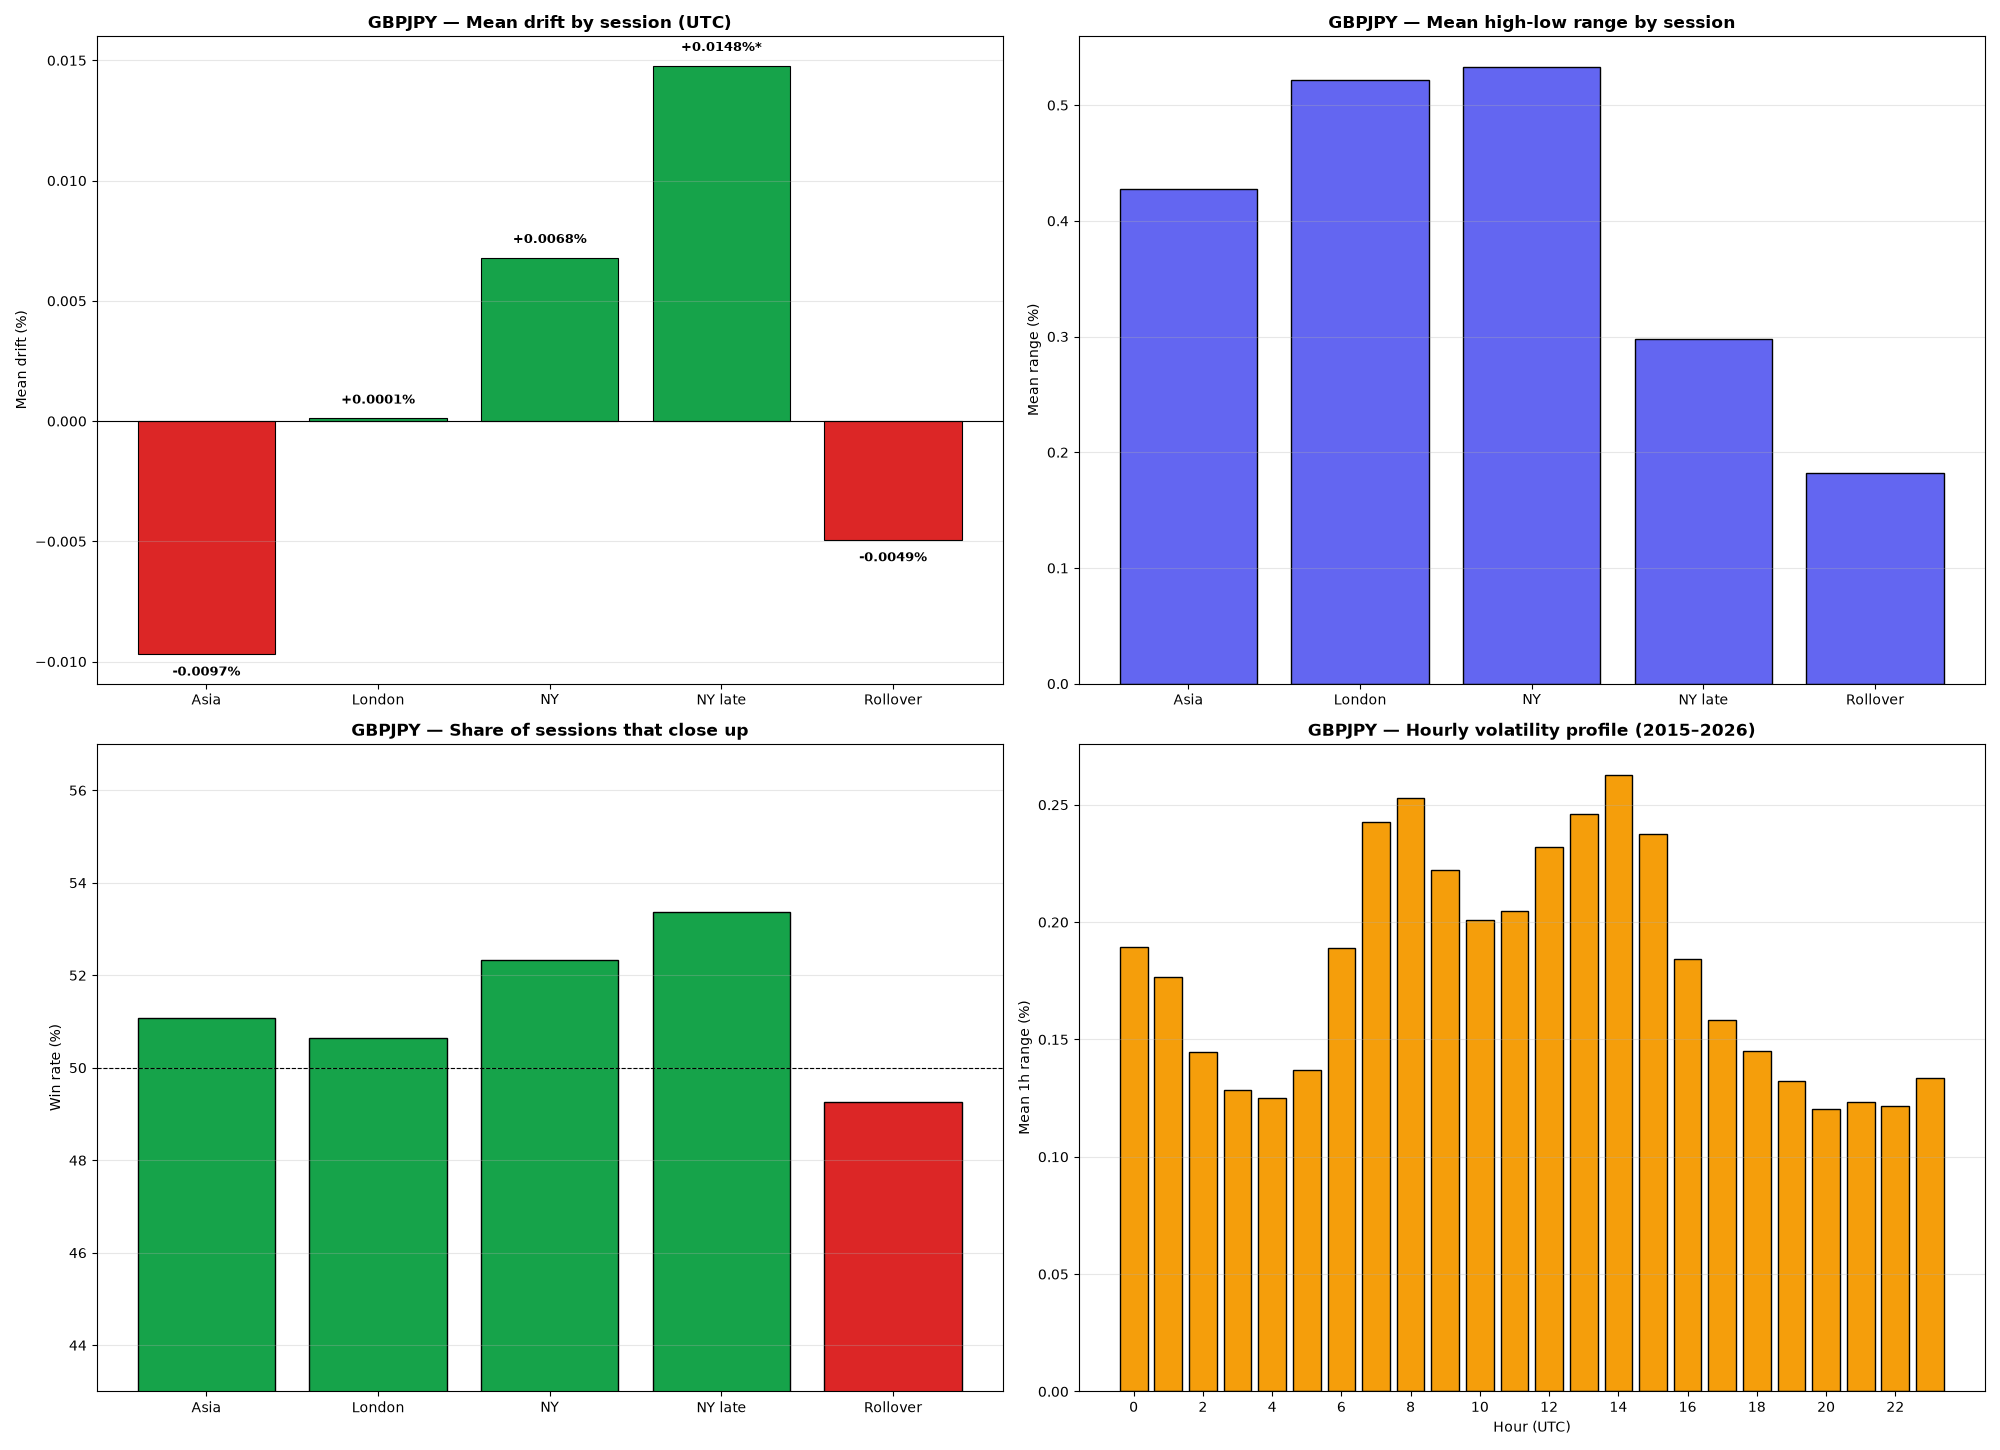
Fixed UTC windows, the same across the whole series. Drift = session close against its open; range = high minus low, as % of the open.
| Session | n | Mean drift % | Win rate | p-value | Mean range % |
|---|---|---|---|---|---|
| Asia (00–07 UTC) | 3,064 | -0.0097% | 51.1% | 0.119 | 0.427% |
| London (07–12 UTC) | 3,056 | +0.0001% | 50.7% | 0.986 | 0.522% |
| New York (12–17 UTC) | 3,056 | +0.0068% | 52.3% | 0.299 | 0.533% |
| NY late (17–22 UTC) | 3,056 | +0.0148% | 53.4% | <0.001 | 0.298% |
| Rollover (22–24 UTC) | 2,452 | -0.0049% | 49.3% | 0.130 | 0.182% |
- New York (12–17 UTC) is where it moves: mean range 0.533%, 2.9× that of Rollover (22–24 UTC).
- NY late (17–22 UTC) drifts up with p=<0.001 (+0.0148% per session). It is a small bias: compare it with the spread before thinking of trading it.
4. Day × session heatmap
| Day | Asia (00–07) | London (07–12) | New York (12–17) | NY late (17–22) | Rollover (22–24) |
|---|---|---|---|---|---|
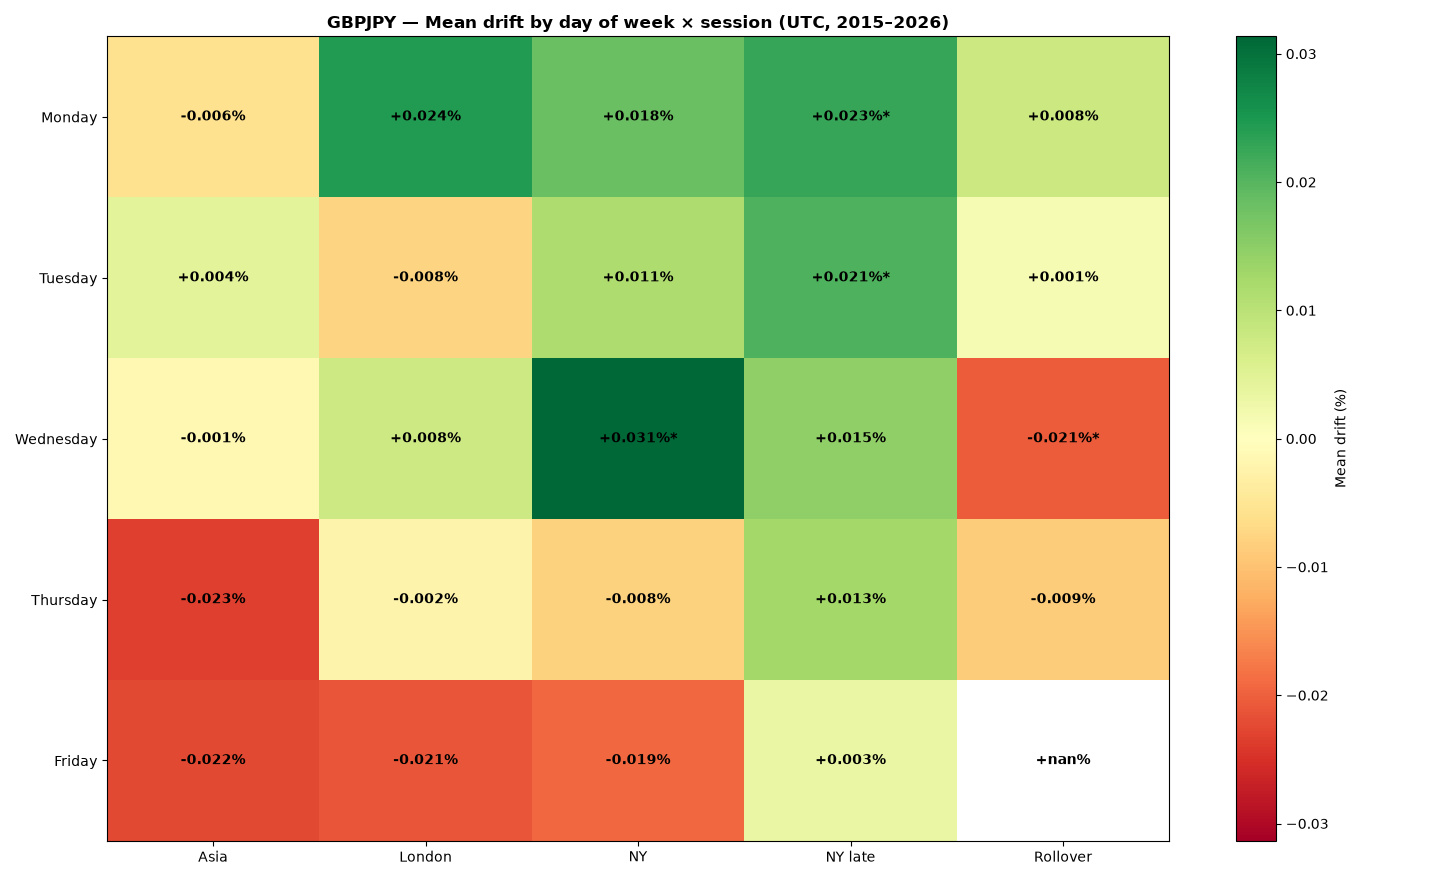
| Monday | -0.006% | +0.024% | +0.018% | +0.023% | +0.008% |
| Tuesday | +0.004% | -0.008% | +0.011% | +0.021% | +0.001% |
| Wednesday | -0.001% | +0.008% | +0.031% | +0.015% | -0.021% |
| Thursday | -0.023% | -0.002% | -0.008% | +0.013% | -0.009% |
| Friday | -0.022% | -0.021% | -0.019% | +0.003% | +nan% |
- Most bullish cell: Monday × NY late (+0.023%, p=<0.001). Most bearish: Wednesday × Rollover (-0.021%, p=<0.001).
- 4 of 25 cells come out at p < 0.05; chance alone would give about 1.2. That is more than chance would produce, but they still need out-of-sample confirmation.
5. Most volatile hours (UTC)
| UTC hour | Mean range % | Mean range (pips) | Std % | Session |
|---|---|---|---|---|
| 14:00 | 0.263% | 42.6 | 0.151 | NY |
| 08:00 | 0.253% | 41.0 | 0.160 | London |
| 13:00 | 0.246% | 40.0 | 0.152 | NY |
| 07:00 | 0.243% | 39.4 | 0.147 | London |
| 15:00 | 0.237% | 38.4 | 0.148 | NY |
| 12:00 | 0.232% | 37.7 | 0.151 | NY |
The busiest hour (14:00 UTC) moves 2.2× more than the quietest (20:00 UTC, 0.120%). Unlike the calendar bias, this is stable year to year: it is the most useful part of this analysis for deciding when to be at the screen or where to place a stop.
6. What it costs to trade: the measured spread
The feed carries real bid and ask, so the spread is measured, not a broker's marketing figure. Median since 2015: 1.70 pips. But a spread in pips does not say how heavy it is: what matters is how much of the hour's typical move it eats.
| UTC hour | Median spread (pips) | Mean range (pips) | Cost |
|---|---|---|---|
| 14:00 | 1.60 | 42.6 | 3.8% |
| 08:00 | 1.60 | 41.0 | 3.9% |
| 13:00 | 1.60 | 40.0 | 4.0% |
| 21:00 | 5.50 | 21.1 | 26.0% |
| 22:00 | 3.20 | 22.1 | 14.5% |
| 20:00 | 2.00 | 19.5 | 10.3% |
Trading at 14:00 UTC costs 3.8% of the hour's range; at 21:00 UTC, 26.0%. The cross-market comparison is in the real spread by market and hour.
What this data does not tell you
- Multiple comparisons: this article runs 47 tests (5 days, 12 months, 5 sessions and 25 cells). At a 5% threshold about 2 would come out "significant" by chance. That is why what survives Bonferroni is flagged separately.
- Few years per month: each month has about 11 observations. One extreme year can create or erase a "bullish month".
- An average bias is not a strategy: after spread, commission and swap, a drift of hundredths of a percent per session rarely survives. Before trading it, backtest with real costs and walk-forward.
- Dukascopy bid price: your broker will have a different spread and daily close; with a cut-off other than 22:00 UTC the day-of-week split shifts a little.
Methodology
- Source: Dukascopy ticks aggregated to M1 candles by EV Trading Labs (GBPJPY, 2015-01-01 → 2026-10-12).
- Total: 4,391,067 M1 candles with at least one tick; 3,055 daily and 140 monthly returns.
- Price: open and close at mid price (bid+ask)/2; high and low on the bid. Where the feed has no ask, bid.
- Daily return: (C[t] − C[t−1]) / C[t−1] × 100, where C is the close at 22:00 UTC. Days with fewer than 60 candles, or whose last candle is more than 3 h before the cut-off, are dropped.
- Monthly return: last daily close of the month against the previous month's; the current month is excluded.
- Sessions: drift = (close − open) / open × 100; range = (high − low) / open × 100; sessions with less than 40% of their minutes are dropped.
- Test: one-sample t-test against zero, p < 0.05; Bonferroni per block (days, months, sessions, cells). Stability: the same mean computed on each half of the sample.
- Software: Python, pandas, scipy, matplotlib.
The full seasonality series
The same method applied to 19 markets. The contrast between them is the most useful part: a pattern that shows up in a single asset is more likely to be noise.
- Forex: EURUSD · GBPUSD · USDJPY · AUDUSD · USDCHF · EURGBP
- Metals: XAUUSD (gold) · XAGUSD (silver)
- Indices: Dow Jones · NASDAQ-100 · S&P 500 · DAX 40 · FTSE 100 · Nikkei 225
- Oil: Brent · WTI
- Crypto: Bitcoin · Ethereum